Real estate portfolio diversification is usually explained as a checklist: some residential, some commercial, perhaps a fund. For someone who already owns prime property in one country, that checklist misses the decision actually in front of them, which is where the next holding should sit.
This guide looks at that decision through the evidence on how property markets, currencies and uses behave, and at what owning across borders involves in practice.
What is real estate portfolio diversification?
Real estate portfolio diversification means holding property whose value and income do not all respond to the same forces. If every holding follows the same market cycle, earns in the same currency and serves the same purpose, the holdings amount to one bet made several times over, however many addresses they have.
The usual advice treats diversification as a matter of building types, sectors and funds, and treats property as one asset class to balance against shares and bonds. That framing suits someone building a first investment strategy.
For a private owner with direct real estate already in hand, three other axes do more of the work:
- Market: whether the holdings sit in property markets that move on different cycles.
- Currency: whether their value and rent are earned in more than one currency.
- Use: whether one holding is a home you enjoy and another is held purely as capital.
The old warning about keeping all your eggs in one basket still applies, but the basket is rarely the building. It is the city, the currency and the reason for owning. Good real estate diversification works on all three, and the sections below take them in turn.
Does geographic diversification reduce risk more than mixing property types?
Yes, and the evidence has held for decades. In a study published in the Financial Analysts Journal in 1996, Eichholtz found that real estate returns in different countries are far less correlated with each other than stock or bond returns are. Spreading property internationally therefore cuts risk more than spreading shares internationally does.
More recent work points the same way. Research covering 40 years of data across 13 foreign real estate markets found that foreign real estate has had consistently lower correlation with stocks than foreign equity markets have. Property markets, the authors conclude, “remain relatively segmented”, and portfolios that included foreign real estate did better on a risk-adjusted basis.
In a 2024 review of global real estate, KKR notes that performance “has varied significantly based on property type, region, and portfolio construction”. Both property types and locations matter, but for a private holder the second carries more weight.
This is why geographic diversification does more than spreading across property types in one city. A second flat in the same city diversifies very little. So does a unit of commercial real estate bought across town, which is the usual retail suggestion: it still depends on the same local economy, the same lending conditions and the same bouts of volatility.
Changing the property type or sector without changing the market adds complexity more than protection.
Prime markets rarely move together
The research describes long-run correlations. Recent prices show the same pattern within a single year. Knight Frank’s Prime International Residential Index for 2025 tracked 100 prime residential markets. Prices rose 3.2% on average, against 3.6% in 2024. Of those 100 markets, 73 rose and 24 fell. The Middle East, led by Dubai, performed strongest.
The lesson is not to chase last year’s leader. Market conditions that lift one city can leave another flat, and a local downturn in one place can coincide with steady prices elsewhere.
An owner who holds a real estate portfolio in two unrelated markets accepts that one holding may underperform in a given year while the other holds its value. That spread is the point of owning both.
No index tells you which real estate market will lead next. What the figures do show is that prime property is not one global market moving in step, which is exactly what makes spreading capital across several worthwhile.
Currency: the axis most property holders overlook
Most discussion of diversification stops at location. Yet a property abroad is also a holding in another currency: its value, its rent and its sale proceeds are all earned there. An owner whose wealth sits mostly in one currency changes their currency profile the moment they buy elsewhere, whether they intend to or not.
Morocco offers a clear example. The dirham is not free-floating. According to Bank Al-Maghrib, its central rate is set against a basket of 60% euro and 40% US dollar, and the market rate moves within a band of ±5%.
In practice, a Marrakech holding behaves like an exposure weighted towards the euro and the dollar, inside a managed band. For a holder whose other assets sit in a different currency, that is a distinct profile, and part of what the allocation adds. Currency is not a reason to buy on its own, but it changes the levels of risk you carry.
Spreading your investments across currencies works best when it is deliberate. Before buying, know which currency each holding earns in, which currency you will eventually spend the proceeds in, and how the two relate.
Use: pairing a residence you enjoy with a pure allocation
The third axis is use. A holding can be a residence the owner actually spends time in and lets when away, or it can be held purely as capital. A diversified property mix often includes both, because they answer different needs and create different income streams.
Many of the clients we advise pair the two this way. Marrakech fills the first role: a home for part of the year, with rental income when the owner is elsewhere. Dubai fills the second, as a store of capital. We set out how Marrakech and Dubai complement each other in a separate guide, so that comparison is not repeated here.
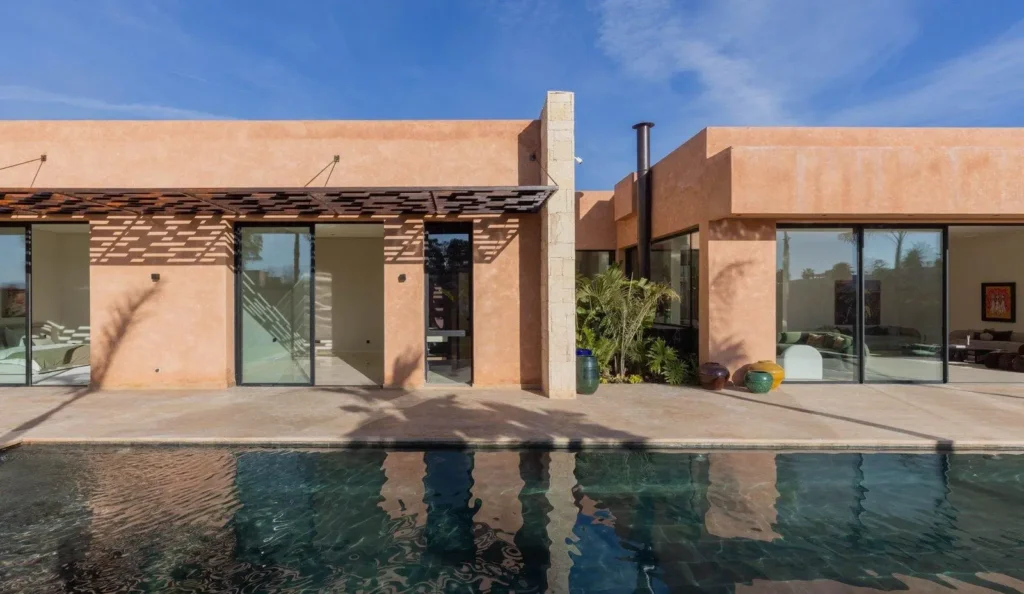
A Dubai holding can also carry a benefit that never appears in a yield calculation. The Dubai Land Department states that property worth AED 2 million, wholly owned across one or more properties, qualifies for a 10-year renewable residence permit. The property may be mortgaged if the bank issues a no-objection letter.
For an internationally mobile family, that right of residence belongs in the arithmetic alongside price and cash flow.
Our own reach follows the same logic. Marrakech is our primary market. In Dubai, a partnership with Preeminent Properties gives access to developments by Emaar, DAMAC, Meraas and Nakheel, which you can see in our Dubai portfolio. In Saudi Arabia, the Four Seasons Private Residences on the Jeddah Corniche add a third market.
For owners who want the lifestyle holding to pay its way, buy-to-let in Marrakech is a holding type in its own right. Its return depends on tenant demand and vacancy rates, so it sits best alongside holdings whose value does not rely on stable cash flows from letting.
Why the next holding rarely belongs in the same market
When an owner decides to buy again, the easiest option is often the market they already know. It is also the one that adds least. A second property in the same market doubles exposure to the same price cycle, the same interest rate environment, the same currency and the same local rules. It adds weight to the basket rather than a second basket.
The correlation evidence explains why. Holdings in one market tend to rise and fall together, so a real estate investment portfolio built in one city behaves like one large holding. When rates rise or local demand weakens, every property in it feels the pressure at the same time.
Costs at home deserve a check too. Some countries charge higher purchase taxes on an additional home, so look at how your country of residence treats a second property before assuming a purchase at home is the cheaper route.
Check as well how it taxes rental income and gains from property investment abroad, and whether a double taxation treaty with the destination country applies. A tax adviser where you live should confirm the answer before you commit.
To diversify your portfolio properly, the next holding should differ from the last on at least one axis that matters: market, currency or use. For the Morocco side of costs and procedure, our guide to buying property in Morocco as a foreigner sets out what a foreign buyer can own and what each step involves.
Owning in several countries: exit, repatriation and management
Buying is the visible part of a cross-border real estate investment. Owning and eventually selling are where the differences between countries show, so it pays to know how money comes out and who looks after the property in between.
On exit, Morocco’s convertibility regime allows capital brought in as foreign currency to be repatriated, together with profits and capital gains, as the State Department’s 2025 country report on Morocco describes. That shapes the risk of loss an owner carries: capital that can come home can be reallocated when your plans change.
The table sets three options side by side, with the points this guide has established for each.
| Holding | Currency exposure | Entry, exit and residency |
|---|---|---|
| A second property where you already own | Your existing currency, so nothing new | A possible surcharge on an additional home; same cycle as your current holding |
| Marrakech | Dirham, managed against 60% euro and 40% US dollar within a ±5% band | Foreign-buyer steps in the buying guide; foreign-currency capital repatriable with profits and gains |
| Dubai | Not covered in this guide | AED 2 million wholly owned qualifies for a 10-year renewable residence permit |
The practical objection to owning in several countries is distance. A property in a country where you do not live needs someone on the ground for letting, upkeep, staff and accounts. Without that, a holding meant to reduce risk becomes a source of it.
This is where the service after the purchase matters as much as the purchase itself. Rental management in Marrakech covers the income side of a home you are not there to run. Real estate asset management takes the wider view, overseeing how each of your real estate assets performs against the reason it was bought.
Alongside advisory and transactions, these make up our investment management offer, so that property management and the wider plan sit with one team.
How to diversify your property portfolio, step by step
There is no reliable rule for how many properties or markets you need. Diversifying is a sequence of decisions, and good real estate advisory starts from what you already hold, not from what is for sale. A practical order:
- Map what you hold by market, currency and use.
- Identify the concentration: one city, one currency or one purpose.
- Choose the next market for what it adds on the missing axis, not for last year’s headline performance. If you want a second view at this point, you can discuss your allocation with our advisory team.
- Settle the exit before you buy: repatriation rules at the destination, and how your country of residence will tax the holding.
- Arrange management before completion, so the property is looked after from the first day.
At Originn Properties, we work one-to-one and take on a limited number of projects at a time. That lets holdings across Marrakech, Dubai and Jeddah be planned as one real estate investment strategy rather than a string of separate purchases.
The aim is a diversified portfolio in the true sense: holdings that reduce risk because they do not all depend on the same economy, the same currency or the same reason for owning. A diversified real estate portfolio is built one deliberate decision at a time.
Real estate portfolio diversification, done this way, is less about adding properties than about choosing what each new one adds. When you are ready to plan yours, begin a private conversation about where your next holding should sit.
Questions investors ask before adding a second market
How many properties do you need to be diversified?
There is no reliable fixed number of properties that makes a portfolio diversified. What matters is how differently the holdings behave, not how many there are. Eichholtz’s research in the Financial Analysts Journal showed that property returns in different countries are far less correlated than stock or bond returns, so two properties in unrelated markets can diversify more than five in one city.
Is real estate portfolio diversification possible within one property type?
Yes. It works when the holdings sit in different countries, because geography, more than type, is what lowers correlation. A 2024 study by Conover and co-authors, covering 40 years of data across 13 foreign markets, found that property markets remain relatively segmented. Prime residential spread across several countries can therefore diversify more than a mix of residential and commercial in one market.
Can REITs diversify a property portfolio?
REITs offer a liquid, listed route to property exposure. A REIT is a share in a fund, though, not a property you own, use or let yourself. For someone deciding where their next home or residence should sit, REITs answer a different question.